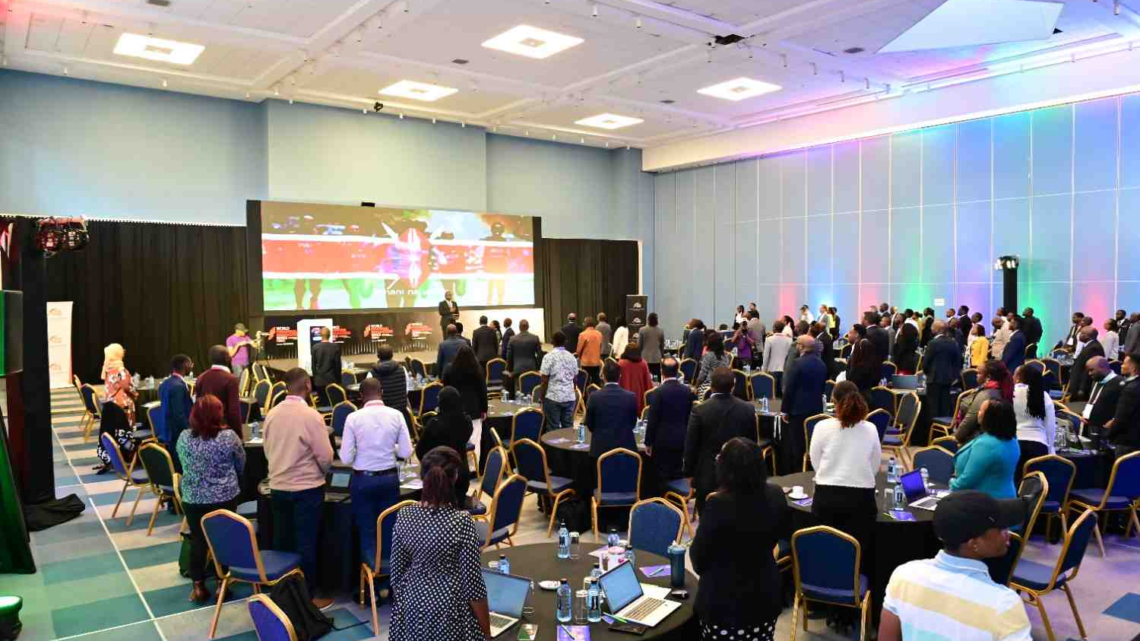
BFSI Event Kenya: Building Smarter Financial Services
August 27, 2026Financial services are being reshaped by digital payments, artificial intelligence, open banking, cloud infrastructure, data analytics, and changing customer expectations. In Kenya, this shift is especially significant as banks, fintechs, insurers, payment providers, and regulators work within a fast-moving ecosystem. A BFSI event in Kenya can help industry leaders understand where this transformation is heading, which technologies are creating measurable value, and how institutions can build services that are faster, safer, more inclusive, and easier to use.
Why Smarter Financial Services Matter
Being digital is no longer enough. Customers expect financial services to offer speed and simplicity. They want instant payments, convenient onboarding, personalised products, reliable mobile access, and responses when something goes wrong. Meeting these expectations requires more than launching another application. It involves redesigning processes from the inside out. Legacy systems, fragmented data, manual approvals, disconnected channels, and slow decisions can limit digital investment.
Smarter financial services connect technology with business objectives. Automation can reduce repetitive work. Analytics can support better credit decisions. APIs can connect financial products with wider ecosystems. Cloud platforms can improve scalability. Artificial intelligence can help detect fraud, personalise engagement, and support employees with faster access to relevant information.
Kenya’s Financial Ecosystem Is Evolving
Kenya has developed a reputation for digital financial innovation, particularly through mobile money and fintech adoption. This creates an environment where traditional institutions and technology-led businesses increasingly compete, collaborate, and learn from one another. The opportunity now extends beyond payments. Lending, insurance, wealth management, remittances, digital identity, embedded finance, regtech, and financial inclusion are becoming important parts of the ecosystem.
Growth also introduces complexity. Institutions must manage cybersecurity threats, fraud, data privacy, operational resilience, regulatory obligations, and customer trust. The challenge is building an architecture and operating model that supports innovation without weakening controls.
Where Technology Can Create Real Value
One important question for BFSI leaders is where technology should be deployed first. A strong strategy begins with a business problem rather than a technology trend. Consider customer onboarding. Digital identity verification, automated KYC checks, and intelligent workflow systems can reduce friction while helping institutions meet compliance requirements.
In lending, alternative data and machine learning models can support more informed risk assessment when used with appropriate governance. Fraud prevention is another critical area. Real-time transaction monitoring, behavioural analytics, and anomaly detection can identify suspicious patterns earlier than traditional rule-based systems alone.
Yet automated models require continuous testing because fraud tactics change rapidly. Customer service also presents an opportunity. AI-powered assistants can handle routine queries, while human teams focus on complex cases that require judgement and empathy. The goal should be to make human interaction more useful.
Building Trust Into Digital Transformation
Innovation without trust can quickly become a liability. Financial institutions handle sensitive information and valuable transactions, making security and governance fundamental. A resilient strategy should include identity and access management, encryption, secure APIs, monitoring, incident response, data governance, and security testing. Institutions should also understand how third-party providers access and store customer data.
Artificial intelligence adds another layer of responsibility. Models used for credit scoring, fraud detection, or customer decisions need oversight. Leaders must consider data quality, bias, explainability, model risk, and accountability. Fast decisions are not useful if the system cannot be governed effectively.
Collaboration Can Accelerate Progress
Financial innovation rarely happens inside one organisation. Banks need technology providers. Fintechs need infrastructure and market access. Insurers need data and digital distribution. Regulators need visibility into emerging business models. Customers ultimately need solutions that work across these boundaries. This makes industry events valuable.
A well-focused BFSI exhibition in Kenya can bring decision-makers, technology companies, financial institutions, regulators, and innovators into the same conversation. Such platforms can encourage practical discussions around implementation, partnerships, compliance, customer experience, and technology.
The strongest conversations are grounded in real business challenges. How can an institution modernise legacy infrastructure without disrupting customers? Which AI use cases can produce measurable returns? How should firms prepare for sophisticated cyber threats? What does responsible financial inclusion look like? These questions matter because they connect innovation with execution.
From Digital Adoption to Intelligent Operations
The next stage of financial transformation will be defined by how well institutions integrate their technologies. Isolated digital tools can improve individual processes, but connected systems can create wider operational gains. A modern institution may combine cloud services, APIs, analytics, automation, digital identity, cybersecurity controls, and AI. Connected data allows teams to make decisions with greater context and speed.
This does not mean every institution needs the same technology stack. Investment should reflect business size, customer needs, regulation, infrastructure, and strategic priorities. A smaller financial provider may gain more from improving core workflows and security than from adopting an expensive collection of emerging tools. The focus should remain on measurable outcomes: lower costs, faster service, improved risk management, customer retention, greater financial access, and sustainable growth.
Preparing Leaders for the Next Phase
Technology changes quickly, but organisational readiness often moves more slowly. Financial institutions need people who understand both financial services and digital systems. They also need leadership teams capable of evaluating technology through commercial, operational, regulatory, and customer lenses. Skills development matters alongside technology investment.
Employees need training in data literacy, cybersecurity, AI governance, digital product management, and emerging financial technologies. Cross-functional teams can bridge business and technical departments. Leadership should set innovation priorities, define success metrics, and establish governance before scaling solutions. Small pilots can test assumptions, reveal risks, and provide evidence before larger investments.
Conclusion
Building smarter financial services is not about chasing every new technology. It is about using the right capabilities to solve customer and business problems while protecting trust, resilience, and compliance. Kenya’s financial ecosystem has a foundation for this phase, but continued progress will depend on collaboration, practical innovation, skilled teams, and responsible execution.
For professionals, a BFSI exhibition in Kenya can provide a setting for discovering solutions, exchanging ideas, and exploring partnerships. World Financial Innovation Series (WFIS) Kenya brings industry stakeholders together around the conversations shaping financial services, helping participants examine how innovation can move from promising concepts to practical outcomes.